biz-financer.com logo
About
Tools
Blog
Business Formation & Growth
Money & Funding
People & Workforce
Protection & Compliance
Tools & Productivity
Contact
Read briefings
Loading...
 logo

Business finance briefings for owners who need clarity before they commit capital, headcount, or structure.

Blogs
Business Formation & Growth
Money & Funding
People & Workforce
Protection & Compliance
Tools & Productivity
Explore
All briefings
Finance tools
FAQ
Tools
Runway calculator
Break-even calculator
Hiring cost calculator
Company
About us
Contact us
Privacy policy
Terms & conditions
© 2026 biz-financer.com. All rights reserved.
HomepageBusiness Formation & GrowthMoney & FundingPeople & WorkforceProtection & ComplianceTools & Productivity

Bad Credit Debt Consolidation Loans: Smart Ways to Manage Payments and Regain Financial Control

By Josh SpenserPublished: May 19, 2026
Share:

You don’t need a perfect credit score to rebuild your financial life—you just need a clearer system than the one that got you stuck.

Debt has a way of multiplying quietly. One credit card becomes three. One late payment becomes fees stacked on fees. Before long, it feels less like managing money and more like surviving it.


That’s where bad credit debt consolidation loans enter the conversation. Not as a magic fix—but as a tool for simplification, structure, and breathing room.


The goal here is simple: fewer payments, more control, and a path that doesn’t feel like financial quicksand.

Let’s break it down into practical, real-world steps you can actually use.


1. “Consolidation is about simplicity, not erasing debt”


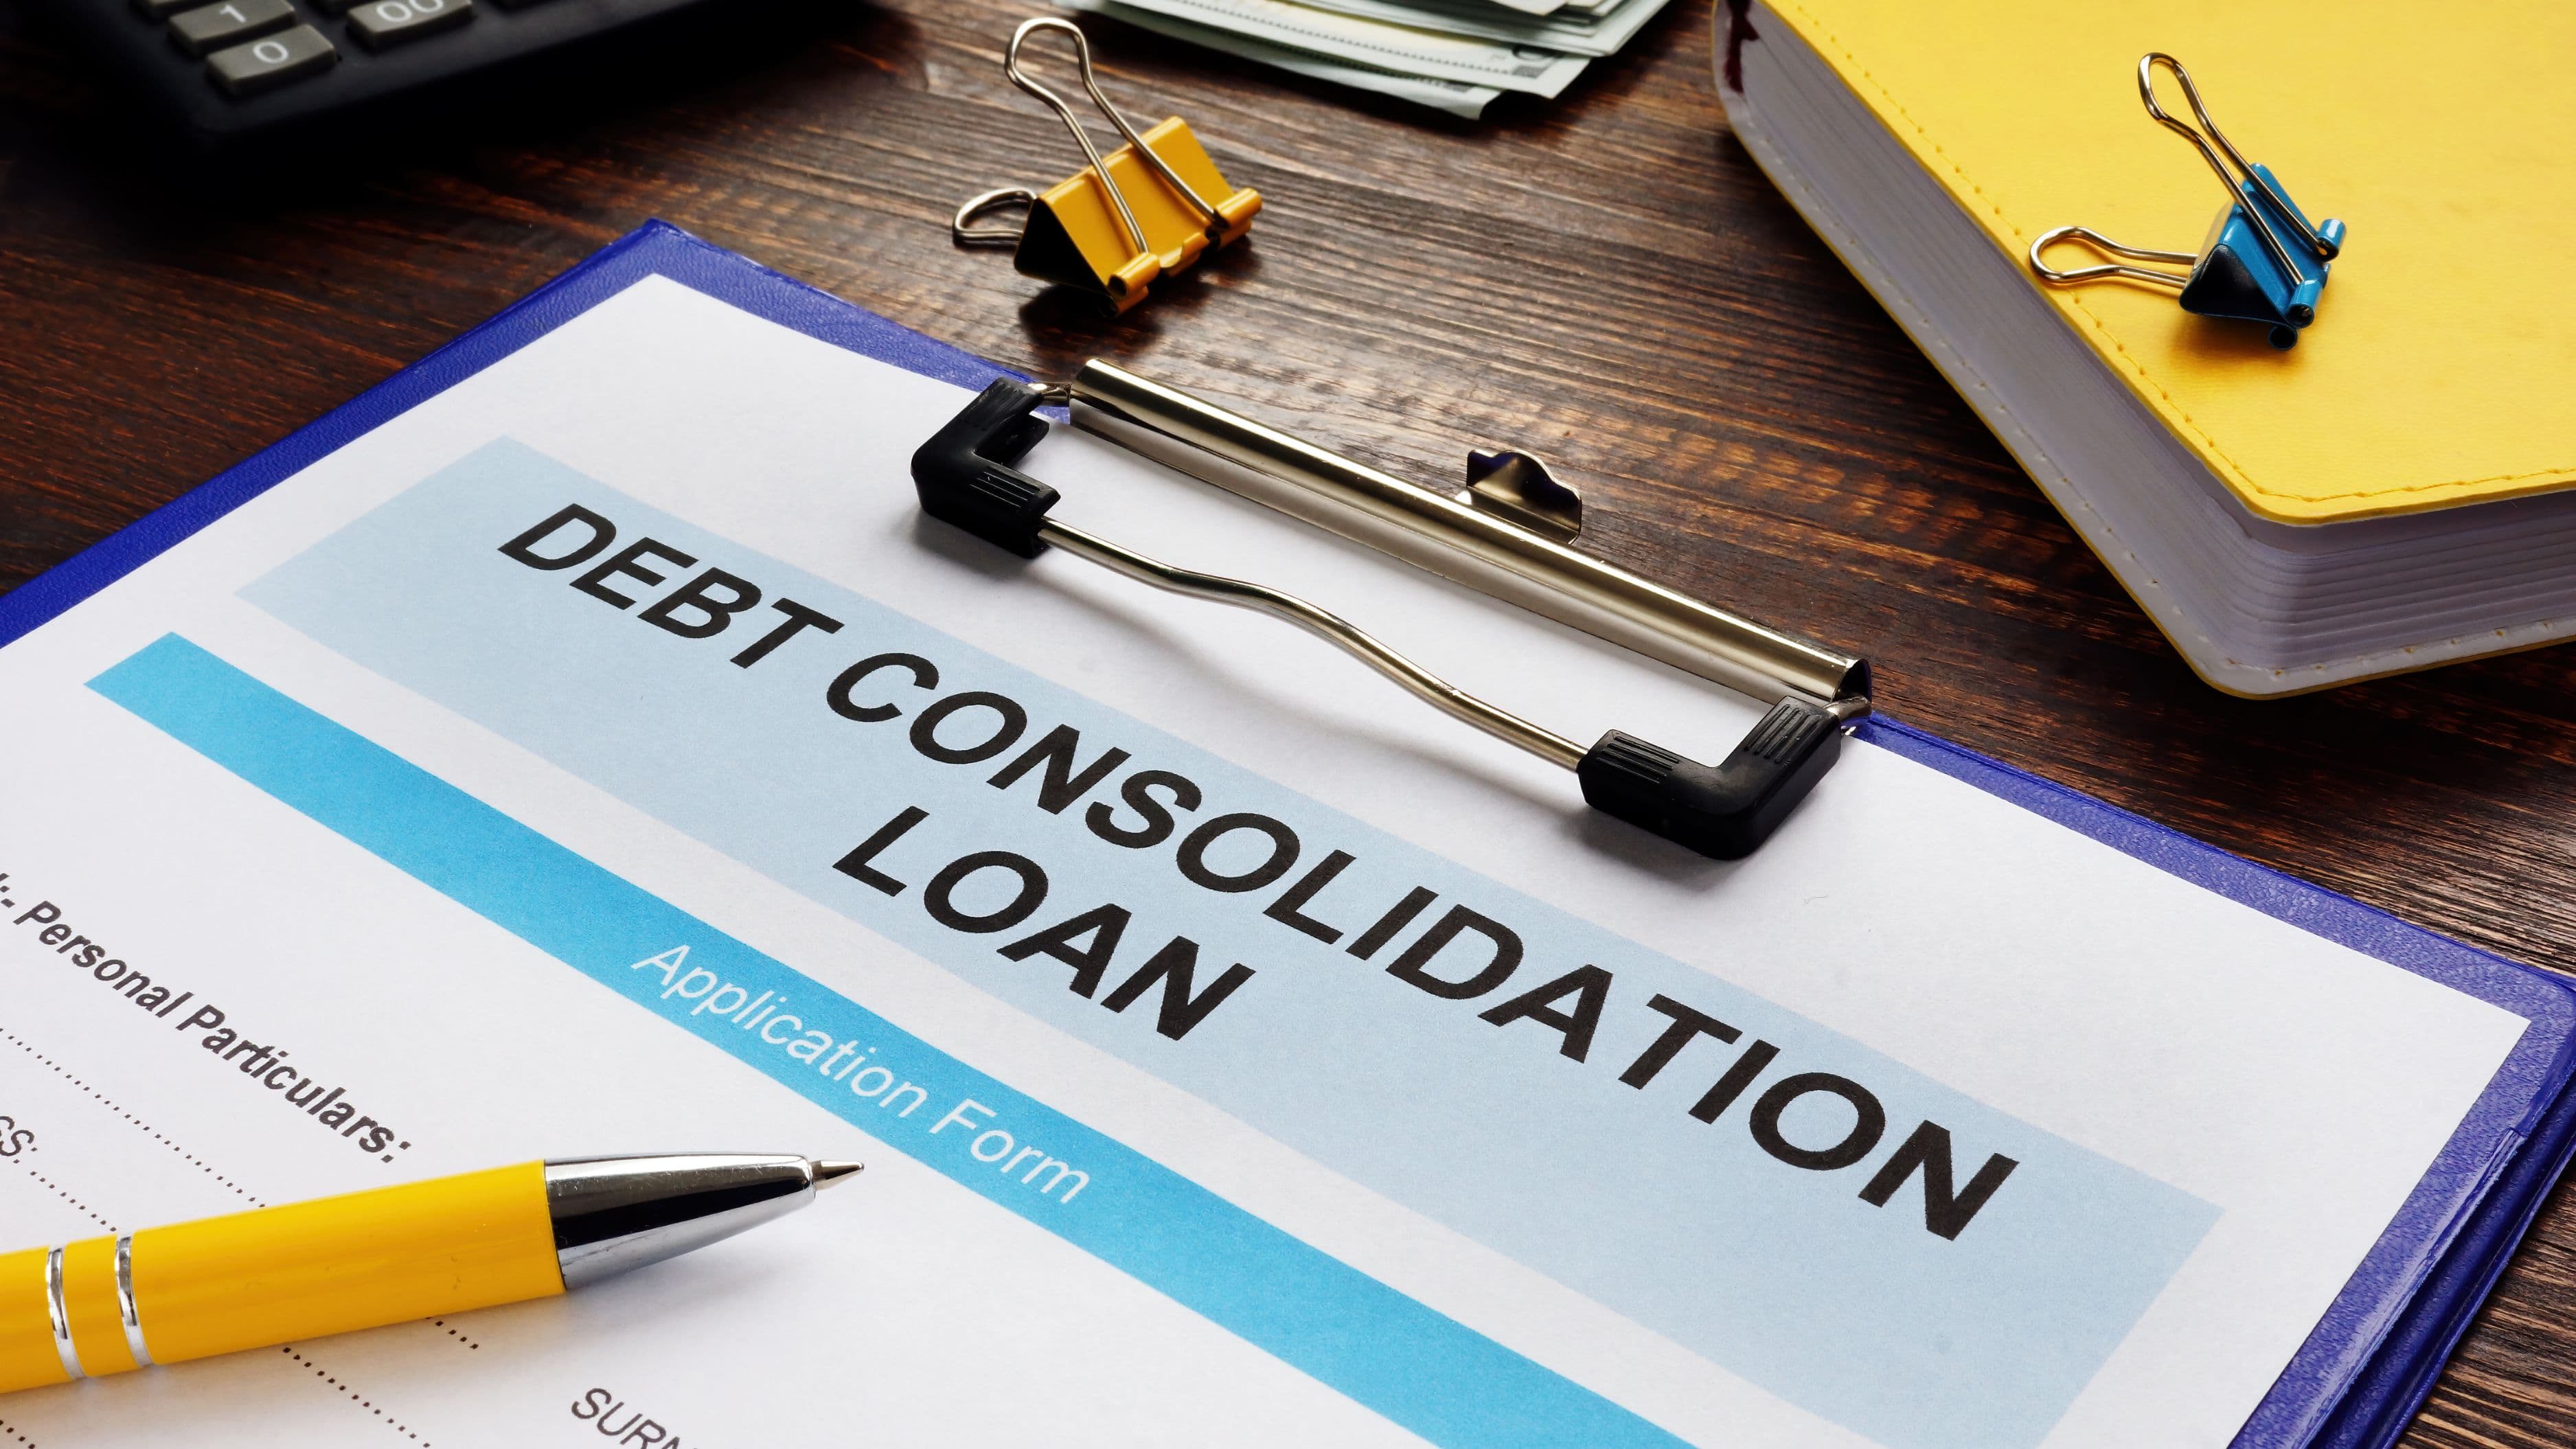
Debt consolidation doesn’t eliminate what you owe—it reorganizes it into one payment. Instead of juggling multiple due dates, you combine debts into a single loan.

This reduces mental load and makes budgeting easier. It’s about clarity, not disappearance.


2. “Your credit score doesn’t define your options”


Bad credit can limit loan choices, but it doesn’t eliminate them. Many lenders specialize in borrowers with low credit scores.

These loans may come with higher interest rates, but they still provide structure and predictability. The key is comparing options, not assuming you have none.


3. “One payment is easier to manage than five stress points”


Multiple debts create multiple deadlines, interest rates, and penalties. Consolidation replaces that complexity with a single monthly payment.

This shift alone often reduces missed payments and financial anxiety. Simplicity improves consistency.


4. “Interest rates matter more than monthly comfort”


A lower monthly payment can feel relieving—but the total interest over time matters more. Some consolidation loans extend repayment terms, which can increase total cost.

Always calculate the long-term impact, not just short-term relief. Financial control requires looking beyond the first bill.


5. “Pre-qualification helps you avoid unnecessary credit damage”


Many lenders allow soft credit checks during pre-qualification. This means you can explore options without hurting your score further.

Only final approval usually triggers a hard inquiry. Smart comparison starts with soft checks.


6. “Secured vs. unsecured loans changes everything”


Secured loans require collateral, like a car or savings account. They often come with lower interest rates but higher risk.

Unsecured loans don’t require collateral but may have higher rates. Choosing between them depends on risk tolerance and financial stability.


7. “Hidden fees can quietly increase your debt”


Origination fees, late penalties, and prepayment charges can affect the true cost of a loan. These aren’t always obvious at first glance.

Reading the full agreement is essential before signing. Transparency protects your long-term budget.


8. “Debt consolidation works best with behavior change”


A consolidation loan alone won’t fix overspending habits. Without adjusting spending patterns, new debt can accumulate quickly.

The loan is a tool—not a solution by itself. Behavior is what sustains results.


9. “Budgeting becomes easier when structure is simplified”


One monthly payment allows you to design a more predictable budget. You can align income, expenses, and savings more clearly.

This structure helps prevent missed payments and overdrafts. Stability grows from predictability.


10. “Lenders look at income stability, not just credit scores”


Even with bad credit, consistent income improves approval chances. Lenders want reassurance that repayment is possible.

Stable employment or verifiable income strengthens your application. Credit score is only part of the picture.


11. “Debt-to-income ratio is your hidden approval factor”


Your debt-to-income (DTI) ratio measures how much of your income goes toward debt. Lower DTI increases approval chances and better terms.

Reducing small debts before applying can improve this ratio. Small adjustments can change outcomes significantly.


12. “Online lenders offer faster but varied terms”


Digital lending platforms often approve loans faster than traditional banks. However, rates and conditions can vary widely.

Speed should not replace comparison. Fast approval still requires careful review.


13. “Credit unions often provide more flexible options”


Credit unions are member-focused institutions that sometimes offer lower rates or flexible terms. They may be more willing to work with bad credit borrowers.

If you qualify for membership, they are worth exploring. Local institutions can outperform large lenders in flexibility.


14. “Avoid borrowing more than you actually need”


It can be tempting to consolidate extra debt “just in case.” But borrowing more increases repayment burden.

Stick to what is necessary for consolidation only. Discipline prevents future strain.


15. “Auto-pay can protect your credit score”


Setting up automatic payments reduces the risk of missed due dates. Even one late payment can negatively affect your credit score.

Automation builds consistency into your financial system. Structure supports discipline when life gets busy.


16. “Emergency funds reduce reliance on new credit”


Even a small savings buffer can prevent future borrowing. Unexpected expenses are often what push people back into debt.

Start small if needed—consistency matters more than size. Savings create financial breathing room.


17. “Loan approval doesn’t mean you should accept it”


Approval is only the first step, not the final decision. Some offers may not actually improve your financial situation.

Evaluate whether the loan reduces stress or simply reshuffles it. Not every approval is a good fit.


18. “Refinancing later can improve your terms”


Once your credit improves, you may qualify for better rates. Refinancing replaces your current loan with a better one.

This rewards progress over time. Financial improvement is dynamic, not fixed.


19. “Debt consolidation is a reset button, not a shortcut”


It reorganizes your financial structure but doesn’t eliminate responsibility. Real progress comes from consistent repayment and better habits.

Think of it as rebuilding your system—not escaping it. Structure is the foundation of recovery.


20. “Small wins build long-term financial confidence”


Paying off consolidated debt on time builds momentum. Each payment strengthens your financial credibility.

Confidence grows through repetition, not perfection. Progress compounds quietly over time.


Conclusion


Bad credit debt consolidation loans can be powerful tools—but only when used with awareness, planning, and discipline.

They don’t erase debt, but they simplify it. And sometimes, simplicity is exactly what financial stress needs most.


If there’s one takeaway, it’s this: control doesn’t come from having fewer problems—it comes from having clearer systems for handling them.

So instead of asking, “How do I fix everything at once?” start with, “How do I make this month easier to manage?”

Because momentum doesn’t start with perfection. It starts with structure.

Pick one and try it right now. Momentum starts small.


📚 Sources

  1. Consumer Financial Protection Bureau (CFPB) – Debt Collection and Debt Relief Guidance

  2. Federal Reserve – Household Debt and Credit Report

  3. National Foundation for Credit Counseling (NFCC) – Debt Management Resources

  4. Experian Credit Education – Debt Consolidation and Credit Score Impact

🔍 Explore Related Topics

  • Debt Consolidation Explained

  • Improve Bad Credit Fast

  • Personal Budgeting Tips

  • Credit Score Recovery Guide

  • Managing Multiple Credit Cards

  • Loan Comparison Strategies

  • Credit Union Loan Options

  • Emergency Savings Basics

  • Refinancing Personal Loans

  • Financial Freedom Planning

Josh Spenser
Josh Spenser

About the Author

Josh Spenser
Josh SpenserRead Full Story

Related Articles

Money & Funding

Do You Actually Need a Business Bank Account?

Do You Actually Need a Business Bank Account?

Updated: May 17, 2026 | Jack Sullivan
Equipment Financing VS. Leasing: a Plain-English Guide

Equipment Financing VS. Leasing: a Plain-English Guide

Updated: July 12, 2026 | Cody Walsh
How Pos Systems Can Actually Cost You More Than They Save

How Pos Systems Can Actually Cost You More Than They Save

Updated: June 28, 2026 | Brittany Hayes
How to Choose the Right Payment App for Your Small Business

How to Choose the Right Payment App for Your Small Business

Updated: May 10, 2026 | Natalie Foster
How to Compare Small Business Lenders Without Getting Overwhelmed

How to Compare Small Business Lenders Without Getting Overwhelmed

Updated: July 5, 2026 | Brittany Hayes

How to Get Funding Without Giving Away Part of Your Business

Updated: May 7, 2026 | Ashley Monroe
How to Get Funding Without Giving Away Part of Your Business

How to Get Funding Without Giving Away Part of Your Business

Updated: May 7, 2026 | Ashley Monroe
How to Get a Business Loan When You're Just Starting Out

How to Get a Business Loan When You're Just Starting Out

Updated: May 3, 2026 | Jack Sullivan
How to Negotiate Better Terms on a Business Loan

How to Negotiate Better Terms on a Business Loan

Updated: July 26, 2026 | Hunter Vaughn
How to Read a Loan Offer Without Getting Confused by the Fine Print

How to Read a Loan Offer Without Getting Confused by the Fine Print

Updated: June 21, 2026 | Megan Carter
How to Send Money Internationally Without Losing a Fortune in Fees

How to Send Money Internationally Without Losing a Fortune in Fees

Updated: May 31, 2026 | Megan Carter
Is a Merchant Cash Advance Ever Worth It?

Is a Merchant Cash Advance Ever Worth It?

Updated: May 7, 2026 | Megan Carter
Prêts DE Regroupement DE Dettes Pour Les Personnes Ayant Un Mauvais Crédit : Des Moyens Judicieux DE Gérer Les Paiements Et DE Reprendre Le Contrôle DE Ses Finances.

Prêts DE Regroupement DE Dettes Pour Les Personnes Ayant Un Mauvais Crédit : Des Moyens Judicieux DE Gérer Les Paiements Et DE Reprendre Le Contrôle DE Ses Finances.

Updated: July 23, 2026 | Brittany Hayes
The Honest Cost of Borrowing Money for Your Business

The Honest Cost of Borrowing Money for Your Business

Updated: May 10, 2026 | Jack Sullivan
What Every Business Owner Should Understand About Cash Flow

What Every Business Owner Should Understand About Cash Flow

Updated: July 26, 2026 | Jack Sullivan
What Happens If You Can't Pay Back a Business Loan?

What Happens If You Can't Pay Back a Business Loan?

Updated: July 12, 2026 | David Harper
What Is Invoice Financing and Can It Help Your Cash Flow?

What Is Invoice Financing and Can It Help Your Cash Flow?

Updated: May 17, 2026 | Hunter Vaughn
What Is Revenue-Based Financing and Is It Right for Your Business?

What Is Revenue-Based Financing and Is It Right for Your Business?

Updated: July 5, 2026 | Ashley Monroe
What Lenders Actually Look at Before Saying Yes to Your Loan

What Lenders Actually Look at Before Saying Yes to Your Loan

Updated: May 31, 2026 | Hunter Vaughn
What's the Difference Between a Business Loan and a Line of Credit?

What's the Difference Between a Business Loan and a Line of Credit?

Updated: May 3, 2026 | Hunter Vaughn
When Does It Make Sense to Hire a Part-Time Financial Advisor?

When Does It Make Sense to Hire a Part-Time Financial Advisor?

Updated: June 21, 2026 | Ashley Monroe
Why Your Business Credit Score Matters More Than You Think

Why Your Business Credit Score Matters More Than You Think

Updated: June 28, 2026 | Ashley Monroe

Bad Credit Debt Consolidation Loans: Smart Ways to Manage Payments and Regain Financial Control

Updated: May 19, 2026 | Josh Spenser

Debt Forgiveness Programs Explained: What Borrowers Are Exploring to Regain Financial Stability

Updated: June 17, 2026 | Josh Spenser

Personal Loan Guide: How to Compare Rates, Qualify Easily, and Borrow Smartly for Your Needs

Updated: May 24, 2026 | Josh Spenser

Smart Debt Consolidation Strategies for People with Bad Credit and Multiple Payments

Updated: May 19, 2026 | Josh Spenser
Do You Actually Need a Business Bank Account?

Do You Actually Need a Business Bank Account?

Updated: May 17, 2026 | Jack Sullivan
Equipment Financing VS. Leasing: a Plain-English Guide

Equipment Financing VS. Leasing: a Plain-English Guide

Updated: July 12, 2026 | Cody Walsh
How Pos Systems Can Actually Cost You More Than They Save

How Pos Systems Can Actually Cost You More Than They Save

Updated: June 28, 2026 | Brittany Hayes
How to Choose the Right Payment App for Your Small Business

How to Choose the Right Payment App for Your Small Business

Updated: May 10, 2026 | Natalie Foster
How to Compare Small Business Lenders Without Getting Overwhelmed

How to Compare Small Business Lenders Without Getting Overwhelmed

Updated: July 5, 2026 | Brittany Hayes

How to Get Funding Without Giving Away Part of Your Business

Updated: May 7, 2026 | Ashley Monroe
How to Get Funding Without Giving Away Part of Your Business

How to Get Funding Without Giving Away Part of Your Business

Updated: May 7, 2026 | Ashley Monroe
How to Get a Business Loan When You're Just Starting Out

How to Get a Business Loan When You're Just Starting Out

Updated: May 3, 2026 | Jack Sullivan
How to Negotiate Better Terms on a Business Loan

How to Negotiate Better Terms on a Business Loan

Updated: July 26, 2026 | Hunter Vaughn
How to Read a Loan Offer Without Getting Confused by the Fine Print

How to Read a Loan Offer Without Getting Confused by the Fine Print

Updated: June 21, 2026 | Megan Carter
How to Send Money Internationally Without Losing a Fortune in Fees

How to Send Money Internationally Without Losing a Fortune in Fees

Updated: May 31, 2026 | Megan Carter
Is a Merchant Cash Advance Ever Worth It?

Is a Merchant Cash Advance Ever Worth It?

Updated: May 7, 2026 | Megan Carter
Prêts DE Regroupement DE Dettes Pour Les Personnes Ayant Un Mauvais Crédit : Des Moyens Judicieux DE Gérer Les Paiements Et DE Reprendre Le Contrôle DE Ses Finances.

Prêts DE Regroupement DE Dettes Pour Les Personnes Ayant Un Mauvais Crédit : Des Moyens Judicieux DE Gérer Les Paiements Et DE Reprendre Le Contrôle DE Ses Finances.

Updated: July 23, 2026 | Brittany Hayes
The Honest Cost of Borrowing Money for Your Business

The Honest Cost of Borrowing Money for Your Business

Updated: May 10, 2026 | Jack Sullivan
What Every Business Owner Should Understand About Cash Flow

What Every Business Owner Should Understand About Cash Flow

Updated: July 26, 2026 | Jack Sullivan
What Happens If You Can't Pay Back a Business Loan?

What Happens If You Can't Pay Back a Business Loan?

Updated: July 12, 2026 | David Harper
What Is Invoice Financing and Can It Help Your Cash Flow?

What Is Invoice Financing and Can It Help Your Cash Flow?

Updated: May 17, 2026 | Hunter Vaughn
What Is Revenue-Based Financing and Is It Right for Your Business?

What Is Revenue-Based Financing and Is It Right for Your Business?

Updated: July 5, 2026 | Ashley Monroe
What Lenders Actually Look at Before Saying Yes to Your Loan

What Lenders Actually Look at Before Saying Yes to Your Loan

Updated: May 31, 2026 | Hunter Vaughn
What's the Difference Between a Business Loan and a Line of Credit?

What's the Difference Between a Business Loan and a Line of Credit?

Updated: May 3, 2026 | Hunter Vaughn
When Does It Make Sense to Hire a Part-Time Financial Advisor?

When Does It Make Sense to Hire a Part-Time Financial Advisor?

Updated: June 21, 2026 | Ashley Monroe
Why Your Business Credit Score Matters More Than You Think

Why Your Business Credit Score Matters More Than You Think

Updated: June 28, 2026 | Ashley Monroe

Bad Credit Debt Consolidation Loans: Smart Ways to Manage Payments and Regain Financial Control

Updated: May 19, 2026 | Josh Spenser

Debt Forgiveness Programs Explained: What Borrowers Are Exploring to Regain Financial Stability

Updated: June 17, 2026 | Josh Spenser

Personal Loan Guide: How to Compare Rates, Qualify Easily, and Borrow Smartly for Your Needs

Updated: May 24, 2026 | Josh Spenser

Smart Debt Consolidation Strategies for People with Bad Credit and Multiple Payments

Updated: May 19, 2026 | Josh Spenser